Selling an accounting practice does not always mean handing over the keys and walking away. Some owners want a clean exit. Others prefer to sell only part of the practice, release some of the value they have built and remain involved for several more years. The choice between a full sale and a partial sale should not begin with the biggest headline offer. It should begin with what you want your finances, responsibilities and working life to look like afterwards.
A full sale can create a clearer route to exit and usually releases more capital at completion. A partial sale can provide liquidity while preserving exposure to future growth. Neither is automatically better. The right answer depends on your goals, your practice, the buyer and the terms around control, payment and the second exit.
Key takeaways
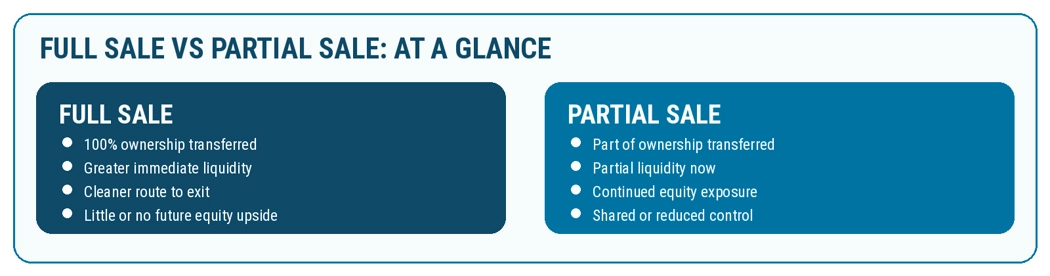
- A full sale transfers the whole ownership interest; a partial sale leaves the seller with continuing equity.
- Full sales usually offer greater immediate liquidity and a clearer route to exit.
- Partial sales preserve possible future upside, but they also preserve business risk and dependency on the buyer.
- Retaining shares does not necessarily mean retaining control.
- The eventual sale of retained equity should be negotiated before the first transaction completes.
Full sale and partial sale explained
In a full sale, you transfer your entire ownership interest to the buyer. You may remain for an agreed handover period, but economically the practice is no longer yours. This often suits owners who are ready to retire, change direction or remove most of their exposure to the future performance of the firm.
A partial sale is more flexible. You might sell a minority stake, sell a majority stake while retaining equity, or agree a phased transaction in which the buyer acquires the rest later. The ownership percentage alone therefore says little about the quality of the deal.
Before comparing structures, establish a realistic view of what the business is worth. Sell Practice’s accounting practice valuation guide explains how recurring fees, profitability, client quality, systems and owner dependency can influence buyer appetite.
Start with your personal outcome
The cleanest way to compare a full sale with a partial sale is to work backwards from the life you want afterwards. If you are genuinely ready to stop running the practice, retaining equity can create obligations you no longer want. If you still enjoy the work and believe the practice has room to grow, selling everything today may feel premature.
Think about the amount of capital you want to release now, the number of years you want to remain involved and how much uncertainty you are willing to accept. Proper exit planning is useful here because it separates the emotional question of leaving a business you built from the commercial question of how to structure the transaction.
Liquidity now versus value later
A full sale usually gives you the greatest opportunity to convert the value of the practice into cash or agreed consideration today. That can be attractive when retirement planning, diversification or financial certainty matters more than future upside.
A partial sale monetises part of the business now while leaving you with a stake that may rise in value. That retained equity is not free upside: you remain exposed to client losses, margin pressure, integration problems and the new owner’s decisions.
The practical comparison is therefore not simply ‘more money now’ versus ‘more money later’. It is certainty versus continued exposure. If future payments are also linked to performance or client retention, read the Sell Practice guide to earn-outs in accounting practice sales before treating the headline price as guaranteed value.
Control can change before ownership ends
Partial sellers sometimes assume that keeping shares means keeping control. That is not always true. If you sell a majority stake, you may remain a significant shareholder while losing the final say on budgets, senior hiring, acquisitions, technology investment, dividends or a future sale of the wider group.
Minority transactions can also introduce consent rights and reporting obligations. A good partner may bring capital, leadership and scale, but the governance still needs to match the way you want to work.
Ask yourself a difficult but useful question: if the buyer makes a decision you strongly disagree with, what can you actually do? The answer should be clear in the deal documents, not left to goodwill.
Your role after completion
A full sale may still involve a transition period because clients and staff often value continuity. The difference is that the transition normally has a defined end point. A partial sale can require a much longer working relationship because the buyer may be investing partly in your ability to continue leading the practice.
Be precise about what ‘staying involved’ means. Will you manage the team, win clients or maintain key relationships? How many days will you work, who controls remuneration and what happens if you want to reduce your hours?
If the purpose of selling is to remove day-to-day pressure, make sure the proposed role genuinely achieves that. A smaller shareholding does not automatically create a smaller workload.
Do not ignore the second exit
The most important issue in many partial sales is not the first transaction. It is the second one. If you keep 20%, 30% or 40% of the practice, how will you eventually turn that stake into cash?
The agreement should address when you can sell, who can buy, how the retained interest will be valued, what happens if you retire earlier than planned and whether you can participate if the majority shareholder sells the wider business. It should also deal with situations where the relationship deteriorates or your circumstances change.
This is why a partial sale should be viewed as a two-stage exit. The first transaction only works if the path to the final transaction is commercially sensible as well.
Clients, staff and transferability
The best structure on paper can still underperform if clients or employees react badly. Accounting practices are relationship-driven businesses, so buyers care about how easily revenue and responsibilities transfer away from the owner.
A partial sale can provide visible continuity because you remain involved, while a full sale may require a more carefully managed handover. In either case, strong second-line leadership, consistent client ownership across the team and documented processes reduce dependency on one person.
Preparing those areas early also helps during buyer review. Sell Practice’s guide on preparing an accountancy practice for sale covers the financial, client, team and operational work that can strengthen marketability before a transaction begins.
Compare the whole deal, not the headline
Two offers can imply the same valuation and still produce very different outcomes. One may pay more at completion but include a long earn-out. Another may ask you to retain equity but give you strong contractual rights around the future sale of that stake.
Compare cash at completion, deferred consideration, earn-outs, retained equity, salary or consultancy income, dividend rights, restrictive covenants and the obligations attached to future payments. Also consider who carries the downside if client retention or profitability changes.
Serious buyers will investigate the business regardless of whether they purchase all or part of it. A structured due diligence process around financial health, client quality, operations, compliance and contracts can prevent surprises from weakening your negotiating position.
When a full sale may fit better?
A full sale often makes more sense when you are ready for a defined exit, want to release the maximum practical amount of value now, no longer want responsibility for major decisions or would prefer not to rely on the future performance of the practice after completion.
It can also be the simpler route when the buyer is a strong cultural fit and the offer gives you sufficient financial certainty. The trade-off is straightforward: once you sell the whole practice, most future equity upside belongs to somebody else.
When a partial sale may fit better?
A partial sale can suit an owner who still wants to work, believes meaningful growth remains and wants a partner to help provide capital, technology, recruitment capability or management depth. It can also support a phased retirement by moving ownership and responsibility gradually rather than all at once.
However, the buyer relationship matters more because you may be working together for years. Cultural alignment, governance and the second-exit mechanism should therefore carry as much weight as valuation. If you are also considering combining with another firm rather than selling a stake, Sell Practice’s guide to selling versus merging an accounting practice explains that separate choice.
How to make the decision?
Reduce the decision to five practical tests. First, how much liquidity do you need now? Second, how much control are you willing to give up? Third, how long do you actually want to remain involved? Fourth, how confident are you in the future growth case? Fifth, exactly how will you sell any retained equity later?
If one structure looks attractive only because of the headline valuation, keep digging. A good transaction should still make sense after you model the cash you receive, the work you must do, the risk you retain and the options you have if circumstances change.
A specialist accountancy practice broker can help qualify buyers, compare structures and keep the negotiation focused on the total outcome rather than a single multiple.
Conclusion
The decision between a full sale and a partial sale is about liquidity, control, time and risk. A full sale can provide a cleaner break. A partial sale can preserve future upside and create a more gradual transition. Both can work well when they are aligned with the owner’s actual objectives.
Start with the future you want, establish the practice’s value and then compare structures on their complete economics. The best deal is not necessarily the one with the biggest number on the first page. It is the one that gives you the right combination of certainty, involvement and flexibility for what comes next.